
Start with the route, not the promise
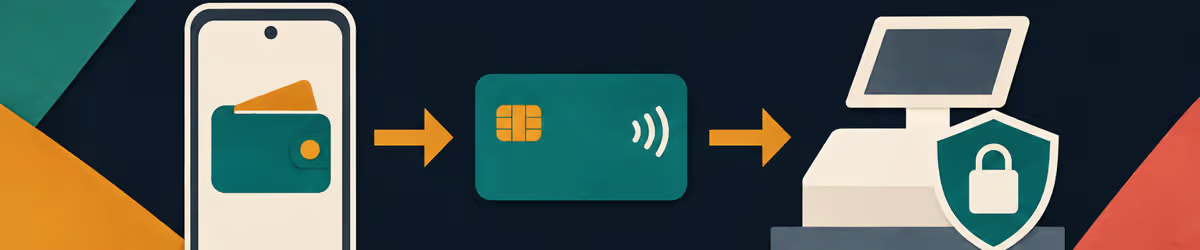
Tokenisation prevents the merchant from receiving the raw card number, but it does not remove the card issuer or account owner from the payment chain.
Availability can depend on device, browser, bank and operator. A payment article cannot prove the option will appear for every signed-in account.
| Visible item | What it may represent | Trace question |
|---|---|---|
| Google Pay logo | Tokenised debit-card deposit | Which card ending is behind the token? |
| Google Pay withdrawal option | Card return supported by that operator | Which masked card receives it? |
| Bank transfer fallback | Separate verified account credit | Which rail and reference? |
| Wallet not shown | Device, browser, bank or operator eligibility | Which condition is unmet? |

The Great Britain rules that shape the answer
The Great Britain credit-card ban still applies to the underlying funding source. Google Pay is not a separate permission layer.
If the transaction is sent to the underlying card, a bank statement may show a processor rather than “Google Pay”. Match the reference and amount.
This page applies to adults in England, Scotland and Wales using businesses licensed for Great Britain. It does not cover Northern Ireland or offshore sites aimed at British users without a UK Gambling Commission licence. Check the exact business and domain in the public register before relying on any process described here.
A practical check sequence
- Identify the underlying debit card in Google Wallet.
- Check Google Pay in both cashier directions.
- Save the masked destination shown after requesting.
- If the wallet option is missing, check device, browser and bank eligibility before assuming a casino error.
- For a missing sent credit, obtain the card or bank reference.
Begin with the casino deposit entry and identify what the operator actually recorded as the funding method. A digital-wallet label, masked card identifier and bank statement description may refer to different parts of the same transaction. Write down those identifiers rather than assuming the physical card's last digits must appear everywhere. Ask support which identifier it uses to locate the original payment.
Then inspect the proposed withdrawal screen. Does it offer a payout through the wallet interface, a return to the underlying card or a bank transfer? The deposit experience does not answer that question. Ask the operator to name the supported route for your account and explain any ownership check. If the card has been replaced, mention that before confirming a destination rather than waiting for a return.
When a payout is described as sent, request a trace reference appropriate to that route. Give the receiving institution the amount, currency and sending date together with the reference. A casino transaction number may identify the request internally without being searchable by a bank. Ask which kind of reference you have if the receiving provider cannot locate it.
Do not retry a deposit to repair a withdrawal enquiry. That creates a new payment and may generate a second identifier without resolving the first. Likewise, adding a different person's card to a wallet does not fix ownership verification. Keep one record containing the original funding identifier, the accepted payout destination and the evidence of sending. If any of those three points is unclear, ask the provider responsible for that stage to clarify it. The aim is a traceable route rather than a guess based on a familiar wallet logo.
If support refers to a token, ask whether it is describing the saved payment credential or the outgoing transfer reference. Those identifiers serve different purposes. Record the explanation in the case file so a later agent does not mistake proof of the funding card for proof that a payout was sent.
Limits, fees and evidence
A method name alone does not prove a fee, minimum, maximum or speed. Those figures can change by operator, customer, currency and account status. Read the current logged-in cashier and terms. Record what was shown on the date of the transaction; do not copy an old comparison table into a complaint as if it were your contract.
Keep a redacted copy of the transaction ID, exact status, amount, time, method, masked destination, relevant terms and written replies. Store identity documents separately from ordinary screenshots. Send them only through the secure channel identified on the licensed domain.
Common mistakes
- Do not assume the Google Wallet balance receives casino funds.
- Do not use a credit card underneath the wallet for GB gambling.
- A phone replacement can change the token presented to the operator.
- Avoid screenshots showing unrelated cards or personal notifications.

Frequently asked questions
Can I withdraw to Google Pay?
Operator support varies. The credit may go to the card behind the wallet or by bank transfer.
Why is the option missing?
The device, browser, bank, card or operator configuration may not be eligible. The signed-in cashier is decisive.
Is Google Pay anonymous?
No. Tokenisation hides the raw card number from the merchant, but the payment remains linked to an account and identity checks still apply.
Why does the withdrawal show a card instead of Google Pay?
The wallet may have been only the tokenised entry route. Confirm whether the masked destination matches the underlying debit card before reporting the payout as misdirected.
Continue through the casebook
- Compare all UK casino payment routes
- Debit card casino deposits and withdrawals in Great Britain
- Apple Pay casino payments: follow the underlying card
- Closed-loop casino withdrawals explained
- Casino payment-method verification without guesswork
Sources checked
- Google Pay casinos — tokenised-card caveat — checked 16 November 2026.
- UK Gambling Commission — Preventing credit card use — checked 16 November 2026.
- Google Wallet Help — payment methods — checked 16 November 2026.
This is general editorial information, not legal or financial advice. Gambling can cause harm. If the task is no longer about a payment record but about stopping, use the responsible gambling help page.