
Start with the route, not the promise
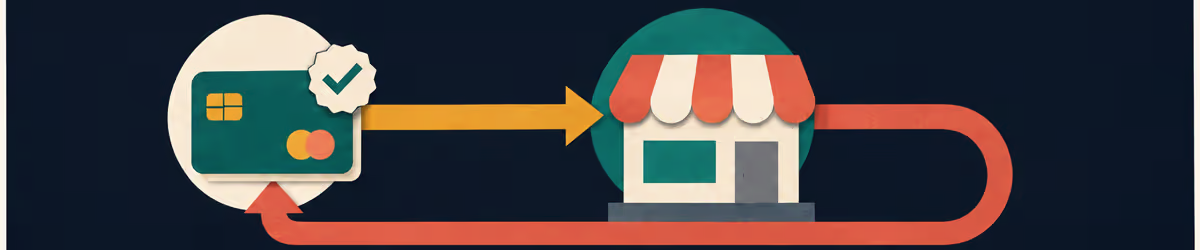
Operator help pages show how varied the implementation can be. Some return funds to each prior deposit method up to deposited amounts; others identify one active method and use bank transfer when a direct return is unavailable.
Using someone else’s card, wallet or bank account can create a serious ownership problem. Do not try to work around it by adding another person’s method. Ask the business how to regularise the account and preserve its written answer.
| Situation | Likely treatment | Question |
|---|---|---|
| One active deposit card | Return where supported | Can this card receive credits? |
| Several deposit methods | Split or prioritised return | How is the amount allocated? |
| Deposit-only wallet or voucher | Verified fallback | Which bank/card route is allowed? |
| Expired or closed method | Return attempt or replacement route | What proof of closure is accepted? |
| Third-party method | Likely ownership review | Why was it accepted and what correction is required? |

The Great Britain rules that shape the answer
Split payouts can produce several statement credits. Match the sum, references and destinations before reporting a shortfall.
A method that cannot receive money should have a clear fallback. If the business did not disclose it before deposit, include that fact and the saved terms in a formal complaint.
This page applies to adults in England, Scotland and Wales using businesses licensed for Great Britain. It does not cover Northern Ireland or offshore sites aimed at British users without a UK Gambling Commission licence. Check the exact business and domain in the public register before relying on any process described here.
A practical check sequence
- Export or screenshot the deposit history.
- List each method, date, amount and account owner.
- Ask how the withdrawal will be allocated before submitting a large request.
- Confirm the fallback for any deposit-only route.
- After processing, reconcile all partial credits against the total.
Limits, fees and evidence
A method name alone does not prove a fee, minimum, maximum or speed. Those figures can change by operator, customer, currency and account status. Read the current logged-in cashier and terms. Record what was shown on the date of the transaction; do not copy an old comparison table into a complaint as if it were your contract.
Keep a redacted copy of the transaction ID, exact status, amount, time, method, masked destination, relevant terms and written replies. Store identity documents separately from ordinary screenshots. Send them only through the secure channel identified on the licensed domain.
Common mistakes
- Do not call every original-route return a legal requirement; policies and risk controls differ.
- Do not use a third-party account to speed up a payout.
- A split payment can arrive on different days.
- A new payment method can trigger a fresh ownership check rather than solve the old one.

Frequently asked questions
Why can’t I choose any bank account?
The business must be satisfied that funds return to the verified customer and may apply an original-route policy.
What if my deposit method cannot receive money?
Ask for the published verified fallback, commonly a personal bank account or eligible card.
Can the withdrawal be split?
Yes under some policies, especially when several methods funded the account. Ask for the allocation and references.
What if several methods funded the account?
List each method and deposited amount, then ask how the operator will allocate the return. Several smaller credits may arrive through different routes and on different days.
Continue through the casebook
- Compare all UK casino payment routes
- How UK casino withdrawals move from request to bank
- Debit card casino deposits and withdrawals in Great Britain
- Casino payment-method verification without guesswork
- Build a casino payment complaint file an adjudicator can follow
Sources checked
- bet365 Help — How do I withdraw? (operator example) — checked 16 November 2026.
- 888 Help — How does the withdrawal process work? — checked 16 November 2026.
- UK Gambling Commission — Key issues and expectations concerning account withdrawals — checked 16 November 2026.
This is general editorial information, not legal or financial advice. Gambling can cause harm. If the task is no longer about a payment record but about stopping, use the responsible gambling help page.